
Managing personal finances once meant collecting paper statements, storing receipts, calling financial institutions, and keeping spreadsheets updated by hand. Today, much of that information can be accessed from a phone or computer within minutes.
The shift toward digital financial tools has changed more than convenience. It has also changed how people organize financial information, monitor investments, communicate with professionals, and think about long-term planning.
Technology can make financial information easier to access and organize, but it does not automatically turn that information into a sound financial plan. The most useful approach combines digital tools with clear objectives, good judgment, and professional guidance where appropriate.
Financial Planning Is Becoming More Digital
Many everyday financial activities can now be completed digitally. Online banking provides access to account balances and transactions, while investment platforms can provide portfolio information without requiring a paper statement.
Financial applications can also bring information from different areas into a more accessible format. The Financial Consumer Agency of Canada notes that some fintech applications can help users manage budgets, track bills, compare financial products, or view multiple financial products in one place. Government of Canada: Financial applications
For someone managing several accounts, this accessibility can make it easier to see the relationship between income, spending, savings, and investments.
However, convenience should not be confused with comprehensive planning. Seeing a portfolio balance is different from understanding whether that portfolio supports a person’s retirement objectives or other long-term goals.
That distinction is where technology and professional financial planning can complement one another.
Tools That Help Organize Financial Information
One of the most practical benefits of financial technology is organization.
People may have information spread across bank accounts, investment accounts, insurance policies, mortgages, registered savings plans, business interests, and real estate. Keeping track of everything manually can become increasingly difficult as financial circumstances become more complicated.
Digital tools can help consolidate information or provide structured ways to record it.
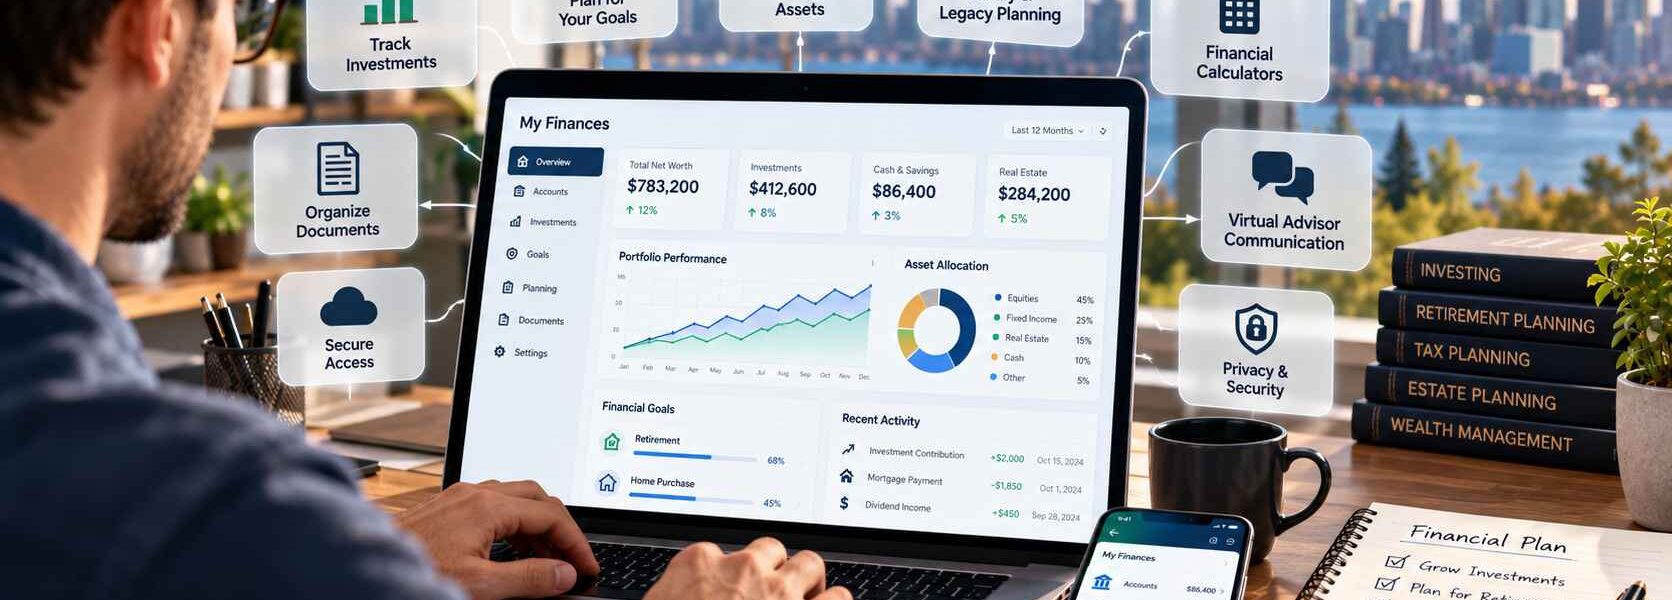
Financial-planning software can be used to model different scenarios. Calculators can help people explore questions involving savings, debt, retirement income, or other financial decisions. Digital document storage can also make important records easier to locate when they are needed.
Some professional wealth-management firms use financial-planning and projection tools to organize this information and examine possible future scenarios. Exponent Investment Management is one example of a wealth-management firm that incorporates financial planning and projection tools into its planning process.
The technology itself is not the plan. It is a way of organizing information and exploring possibilities.
That distinction matters because financial decisions often involve assumptions about income, spending, investment returns, taxes, inflation, retirement timing, and changing personal circumstances. A software output is only as useful as the information and assumptions behind it.
Digital Access and Communication
Technology has also changed the relationship between individuals and financial professionals.
Instead of relying exclusively on in-person meetings, clients may be able to communicate through video meetings, secure portals, electronic documents, email, and other digital channels.
This can make routine communication more convenient, particularly when a person lives far from an advisor’s office or has a demanding schedule.
Digital access can also make it easier to review financial information between formal planning meetings. Someone may be able to check an account, download a statement, review a projection, or securely provide a document without waiting for a paper copy.
The result can be a more continuous relationship with financial information rather than a process that only happens during an annual meeting.
Still, convenience should not replace communication. A financial situation can change because of a new job, business opportunity, marriage, inheritance, property purchase, family responsibility, or retirement decision. Those developments may require interpretation rather than simply an updated account balance.
What Technology Cannot Replace
Financial technology is particularly useful for organizing information, automating calculations, and improving access.
It is less capable of replacing the human context behind financial decisions.
Consider someone who is deciding whether to retire earlier, sell a business, support adult children, purchase another property, or change investment objectives. The decision involves more than numbers.
There may be competing priorities, uncertainty, personal preferences, and questions that cannot be answered by a calculator alone.
Professional planning can provide a structured way to consider those issues. Financial-planning software may help illustrate different scenarios, while a qualified professional can help interpret the assumptions and discuss how different choices could affect the broader plan.
This is particularly relevant as financial lives become more complex. Technology can show what is happening, but people still need to decide what they want their finances to accomplish.
Security and Privacy Considerations
Greater digital access also means people need to pay attention to how financial information is protected.
Online banking and financial applications can involve sensitive information, including account details and personal data. The Government of Canada advises consumers to protect usernames, passwords, PINs, and other banking information, regularly monitor accounts for suspicious activity, and understand the terms and security practices associated with digital financial services.
Consumers should also understand what information an application requests before connecting it to financial accounts.
Not every tool needs access to every piece of financial information. Before using a financial application, it is sensible to understand why access is required, how information may be used, and what protections are available.
Digital organization is most useful when convenience does not come at the expense of privacy or security.
Combining Technology With Professional Planning
Technology can make financial planning more accessible, but its greatest value often comes from supporting a broader planning process.
A professional may use financial-planning software to organize a client’s current position, model potential scenarios, or compare how different assumptions could affect long-term objectives. Digital tools can also help maintain records and make ongoing communication more efficient.
At the same time, professional wealth planning still requires conversations about goals, priorities, risk, family circumstances, retirement expectations, and major financial decisions.
For example, two people with similar incomes and investment balances could have completely different financial priorities. One may be preparing to retire, while another may be building a business or supporting a growing family.
Technology can help organize the numbers, but the meaning behind those numbers depends on the individual.
Making Financial Technology Work for You
The growing availability of digital financial tools gives individuals more visibility into their financial lives than previous generations had.
Banking information can be accessed quickly. Investment portfolios can be monitored online. Calculators can help explore financial questions. Documents can be stored digitally. Financial professionals can communicate remotely. Planning software can model potential scenarios.
These tools can reduce friction and make financial information easier to manage.
But technology should be treated as an enabler rather than a replacement for financial judgment.
A useful financial system combines accurate information, appropriate digital tools, clearly defined goals, and periodic review. As careers, families, investments, businesses, and retirement plans change, the information and assumptions behind a financial plan may need to change as well.
The most effective use of technology is therefore not simply having more financial data at your fingertips. It is using that data to understand your position, ask better questions, and make financial decisions with greater clarity.
For people with increasingly complex financial lives, combining technology with human guidance can turn a collection of digital accounts and documents into a more organized picture of where they are today and where they want to go next.
professional wealth planning can incorporate technology-supported analysis while keeping long-term objectives and personal circumstances at the centre of the planning process.